What is the scope and valuation of the Asteroid Mining Market?
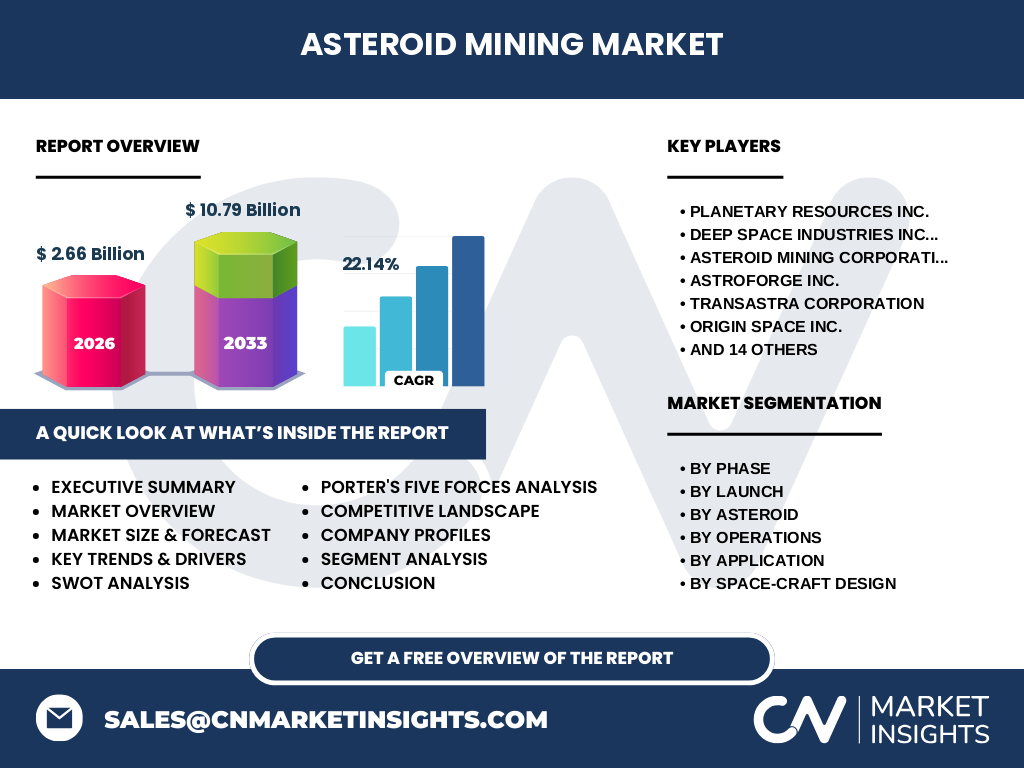
Our analysis indicates that the Asteroid Mining Market is valued at $2.66 Billion in 2026, driven by rising demand for Platinum Group Metals and water extraction in space. The industry encompasses deep-space exploration, proprietary avionics, and extra-terrestrial resource extraction, establishing a foundation for an off-world commercial economy.
Structural Growth Drivers and Market Restraints
The market is propelled by a robust CAGR of 22.14%, scaling to $10.79 Billion by 2033. Primary drivers include declining launch costs and breakthroughs in autonomous prospecting. However, severe regulatory ambiguities under the Outer Space Treaty and extreme capital expenditure requirements remain major commercial constraints.
Emerging Trends and Growth Patterns in Asteroid Mining
The shift toward in-situ resource utilization (ISRU) is redefining mission architectures. Industry pioneers are increasingly focusing on propellant depots in low-Earth orbit, significantly reducing the mass requirements for interplanetary transit and unlocking new revenue models for private space enterprises.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic introduced severe supply chain bottlenecks and delayed critical ground-testing phases for early-stage spacecraft prototypes. However, the subsequent recovery accelerated remote-operations software and automated telemetry systems, ultimately modernizing mission planning protocols across the sector.
Competitive Benchmarking and Market Concentration
The competitive landscape features a mix of agile innovators like AstroForge Inc. and established visionaries such as Planetary Resources Inc. Market concentration remains high among venture-backed startups securing defense grants, while emerging players focus on niche payload delivery and optical navigation software.
Executive Summary of the Asteroid Mining Market
This comprehensive report highlights a transformational valuation surge from $2.66 Billion in 2026 to $10.79 Billion by 2033 at a 22.14% CAGR. Strategic stakeholders must prioritize hardware modularity and regulatory compliance to capitalize on early-mover advantages in extra-terrestrial resource markets.
Market Forecast from 2027 to 2033
Our econometric models project aggressive expansion, lifting the market from its 2026 baseline to $10.79 Billion by 2033. This trajectory is underpinned by anticipated commercial payload milestones by firms like TransAstra Corporation and Karman+ Inc. targeting near-Earth asteroid rendezvous.
Segmentation Analysis Across Operational Phases
The market segments by Phase (Space-Craft Design, Launch, Operations), Launch (Launch Vehicle Selection, Services, Mission Planning), Asteroid Type (Type C, S, M), Operations (Mining, Resource Processing, Data Collection, Transportation), Application (Construction, Resource Harvesting, 3D Printing), and Space-Craft Design (Conceptual Design, Engineering, System Integration).
Regional Market Analysis and Geographic Performance
North America dominates the global footprint, propelled by aggressive NASA funding and private aerospace hubs. Meanwhile, the Asia-Pacific region, spearheaded by entities like Origin Space Inc., demonstrates rapid growth through state-backed lunar and asteroid prospecting initiatives.
In-Depth Regional Review of Advanced Space Economies
United States operations benefit from favorable domestic legislation regarding space property rights. Conversely, European markets leverage collaborative frameworks through the European Space Agency, emphasizing robotic precursor missions and high-precision optical tracking systems for target identification.
Strategic Positioning of Leading Companies
Key industry participants include Asteroid Mining Corporation Limited focusing on legal frameworks and prospecting, alongside Shackleton Energy Company targeting volatile harvesting. These firms leverage proprietary sensor fusion and modular landers to secure competitive advantages in deep-space logistics.
Porter's Five Forces Analysis of the Sector
The threat of new entrants is mitigated by immense capital barriers, yet high supplier power stems from specialized heavy-lift launch providers. Buyer power remains concentrated among space agencies and emerging commercial habitation ventures requiring off-world raw materials.
SWOT Analysis of the Asteroid Mining Ecosystem
Key strengths include breakthrough autonomous robotics and robust venture backing. Weaknesses involve high payload failure rates. Opportunities lie in orbital manufacturing and propellant caching, while threats include orbital debris hazards and evolving international space law disputes.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from ground-based conceptual design and heavy launch services to in-space resource extraction and processing. End-users span orbital construction firms, satellite servicing networks, and terrestrial industries utilizing rare platinum-group metals.
Investment Insights and High-Potential Areas
Investors should target early-stage developers specializing in system integration and autonomous resource processing technologies. Companies capable of demonstrating miniaturized payloads and reliable optical navigation systems offer the highest risk-adjusted return potential through 2033.
Conclusion and Strategic Key Takeaways
Reaching $10.79 Billion by 2033 at a 22.14% CAGR underscores the sector's evolution from theoretical science fiction to a viable commercial frontier. Stakeholders must forge strategic partnerships across the launch and processing segments to mitigate operational risks.
Research Methodology and Baseline Triangulation
Our findings are derived by triangulating trade registry data, primary stakeholder interviews with aerospace engineers, and secondary macroeconomic indicators from global space agencies. This multi-tiered approach ensures high-fidelity market sizing for both near-term valuations and long-term forecasts.
Scope of the Report and Coverage Parameters
This report evaluates the global market across defined operational phases, launch vectors, and asteroid classifications from 2026 to 2033. Limitations include uncertainties surrounding interplanetary payload insurance costs and evolving geopolitical frameworks governing celestial resource utilization.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum features collaborative joint ventures between agile startups and defense contractors focused on heavy-lift rocket optimization. Firms like Celestial Mining and Kepler Energy and Space Engineering have announced advanced telemetry trials aimed at improving deep-space target characterization.